The Chamber of Oil Marketing Companies (COMAC) has called for the immediate and indefinite suspension of Section 136 of the Customs Act, 2026 (Act 1179), arguing that the provision could increase fuel prices, disrupt petroleum supply and undermine government revenue.
COMAC says the provision represents a major change to the downstream petroleum taxation framework but was enacted without what it considers adequate consultation with affected industry players, evidence-based modelling or a published impact assessment.
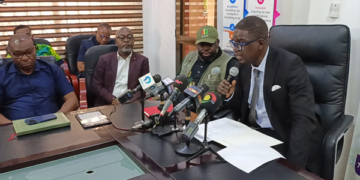
In a statement signed by its CEO and Industry Coordinator, Dr Riverson Oppong, the Chamber said Section 136 changes the point at which downstream petroleum taxes are collected rather than addressing what it identifies as the underlying problem—weak enforcement of existing controls.
Under the new provision, the tax obligation currently borne by Oil Marketing Companies (OMCs) and LPG Marketing Companies (LPGMCs) is transferred to Bulk Import, Distribution and Export Companies (BIDECs).
BIDECs would account for the taxes at the point of sale, with the Commissioner-General of the Ghana Revenue Authority (GRA) permitted to defer payment for up to 21 days against a bank guarantee.
COMAC argues that the change would shift the tax liability to the bulk-supply level, concentrating a significant tax burden at a single point in the petroleum supply chain.
The Chamber says this could create additional financing and guarantee costs for BIDECs, which could eventually be passed on to consumers through higher pump prices.
The Chamber has outlined six major concerns about the new arrangement.
First, it disputes the assumption that transferring tax obligations to BIDECs would necessarily reduce the number of entities involved in tax collection, arguing that the law places no statutory limit on the number of BIDECs.
Second, COMAC fears the measure could lengthen the revenue collection cycle.
It says marketers currently remit within 21 days and often operate on a cash-and-carry basis, while some BIDECs have indicated they may require at least 45 days.
Third, the Chamber describes the new structure as creating a potential “single point of failure”, arguing that the deactivation of one BIDEC could affect several marketers and retail outlets, unlike the current system where individual defaulting marketers can be restricted through the Integrated Customs Management System (ICUMS).
COMAC also says the new arrangement could increase pump prices because BIDECs would have to pre-finance taxes before receiving payment from customers.
It further raises concerns about possible additional collateral requirements under Section 136(5).
The Chamber has also raised legal concerns over what it describes as potentially conflicting tax triggers between Section 126(6) and Section 136 of the Act.
Finally, it says no impact assessment, explanatory memorandum, transitional plan or financing arrangement has been made available. COMAC maintains that the accumulation of tax arrears is primarily an enforcement issue rather than a problem with the existing tax collection model.
According to the Chamber, ICUMS already provides mechanisms such as credit limits and automated restrictions, but these controls were allegedly undermined by system overrides that allowed some operators to exceed approved limits.
“Shifting the collection point does not address this challenge,” COMAC said.
The Chamber wants override access to be restricted, properly authorised, time-bound and fully traceable, arguing that failure to do so could reproduce the existing problem on a larger scale.
COMAC has also renewed questions about what it describes as outstanding issues within the existing petroleum revenue assurance system.
It says its analysis of industry data for the 2025 financial year identified an estimated 819,248,990 litres of unaccounted-for product, with an associated revenue implication of approximately GH¢2.5 billion.
The Chamber says it submitted the findings but has not received a substantive response four months later.
It has also demanded information concerning 10 diesel tankers impounded in October 2025, including their registration details, ownership and the marketers to whom they were designated.
COMAC is additionally seeking clarification over the granting of non-bonded status to three operators, which it says appears to depart from published criteria.
COMAC is asking the Finance Minister to publicly announce the immediate and indefinite suspension of Section 136.
It wants the existing framework retained, under which BIDECs pay import duties and port charges at importation while OMCs and LPGMCs continue to account for taxes and levies ex-pump.
The Chamber is also demanding full disclosure of how operators were permitted to lift petroleum products beyond approved credit limits and payment deadlines, as well as an independent review of non-bonded status grants and material system overrides.
It further wants a formal response to its concerns over the unaccounted product and the 10 impounded diesel tankers.
COMAC says it has placed its members on alert and expects the Ministry of Finance to announce the suspension of Section 136 within 14 days.
Failure to do so, it says, will lead to an emergency general meeting of its members to determine the next steps through administrative, regulatory and legal channels.
The Chamber stressed that it does not intend to disrupt petroleum supplies, given the essential role its members play in the economy.
However, it said the industry cannot operate confidently under what it considers an untested and insufficiently explained framework.
“COMAC considers Section 136 to be a transfer of risk, not reform,” the Chamber said, insisting that existing controls should first be enforced, system overrides and exceptions made transparent, and outstanding product discrepancies fully accounted for before any replacement of the current system is considered.