CUTS International, Accra, has welcomed the Ghana Revenue Authority’s (GRA) real-time tax collection on taxable cross-border digital services but is urging the government to review the 20% charge on tuition for recognised foreign distance-learning programmes.
In a statement on Thursday, October 15, the policy think tank said the collection arrangements would help protect Ghana’s revenue base and promote fair competition, stressing that they do not introduce a new tax.
The combined 20% charge comprises 15% Value Added Tax (VAT), a 2.5% National Health Insurance Levy and a 2.5% GETFund levy.
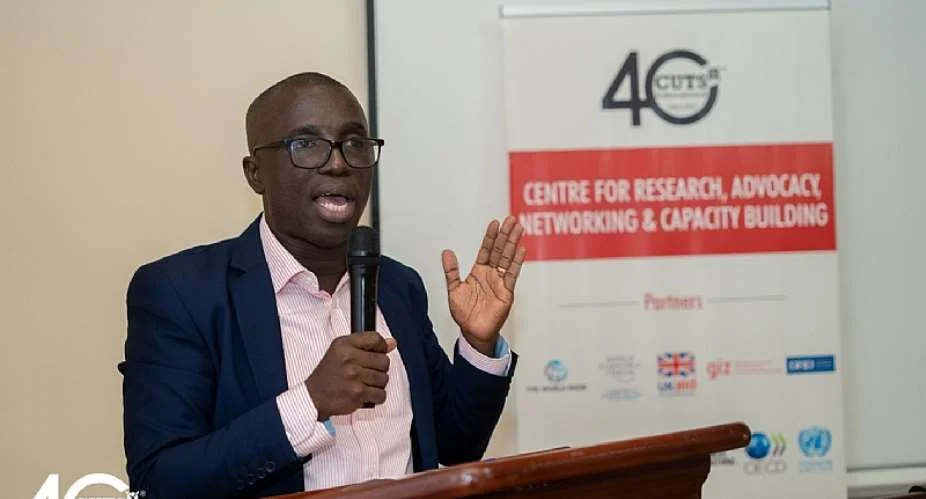
Appiah Kusi Adomako, Esq., Director of CUTS International’s West Africa Regional Centre, said, “A software purchase should not escape tax because the customer receives a download instead of a CD. As commerce moves online, tax collection must follow. Leaving taxable digital imports outside effective collection would create a growing hole in Ghana’s revenue base,”
However, CUTS raised concerns about applying the charge to tuition paid by Ghanaian students enrolled in recognised foreign distance-learning programmes, particularly where comparable qualifying education provided locally benefits from VAT exemption.
The organisation cited a University of London tax notice indicating that payments by Ghana-resident students attract the combined 20% charge under Ghanaian tax requirements.
It called on the Ministry of Finance, the GRA and the Ministry of Education to clarify the rules governing exemptions and establish transparent criteria for recognising eligible foreign distance-learning programmes. It also wants any relief to cover the applicable levies, not just VAT.
CUTS further urged the GRA, banks and payment providers to prevent duplicate taxation and promptly refund wrongful deductions.
“A tax system earns public trust when errors are corrected quickly. The GRA deserves commendation for including a resolution process. Banks must make complaints easy to submit, give customers reference numbers and refund wrongful deductions promptly,” Mr. Adomako said.
The digital tax collection arrangements are intended to improve enforcement of existing tax obligations on qualifying services purchased from suppliers outside Ghana.
CUTS maintains that while taxable digital transactions should be subject to applicable taxes, the use of an online payment channel alone should not determine liability, and existing exemptions must be preserved.